 By Anson Lee
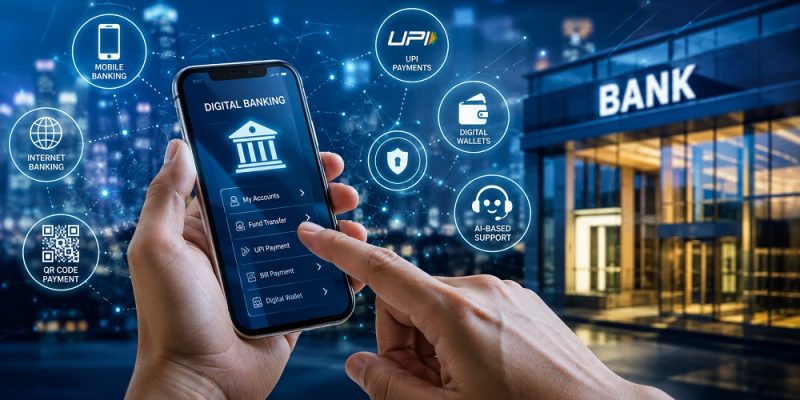
The financial services landscape has undergone a profound structural shift over the past decade. The traditional banking model—defined by physical branch visits, paper documentation, and rigid operating hours—has rapidly evolved into a continuous, digital-first ecosystem. Powered by cloud computing, smartphone technology, advanced data analytics, and artificial intelligence, digital banking has transitioned from a convenience feature into the foundational architecture of global personal and commercial finance.
This digital transformation extends far beyond moving paper statements onto smartphone screens. It has fundamentally restructured how capital moves, how financial products are designed, how risk is assessed, and how institutions interact with consumers. As digital banking matures, it continues to reframe consumer expectations and drive efficiency across every sector of the global economy.
The Core Pillars of the Digital Banking Revolution
The rise of digital banking rests on several key technological and regulatory developments that have collectively dismantled traditional barriers to financial management.
Mobile-First Ecosystems and Instant Accessibility
The near-universal adoption of smartphones introduced continuous access to financial accounts. Modern mobile banking applications allow users to manage funds, execute instant domestic and international transfers, apply for credit, and monitor investment portfolios in real time from any location. This constant availability has eliminated geographic constraints and reduced transaction friction, making daily financial management an effortless task.
Neobanks and Direct-to-Consumer Models
The emergence of neobanks—digital-only financial institutions operating without physical branch networks—has disrupted traditional retail banking. By shedding the high real estate and administrative overhead costs associated with physical branches, these companies offer low-fee or fee-free checking accounts, higher yields on savings, and highly intuitive user interfaces. Their rapid growth has forced legacy financial institutions to modernizing their own digital platforms and rethink fee structures.
Open Banking and API Integration
Open banking frameworks, enabled by secure Application Programming Interfaces (APIs), allow customers to safely share their financial data with third-party financial technology applications. This data interoperability has birthed a rich ecosystem of personal finance tools, automated budgeting apps, robo-advisors, and integrated payment solutions. Instead of relying on a single bank for all financial services, consumers can now easily construct a customized suite of specialized tools tailored to their unique financial goals.
Strategic Advantages of Digital Financial Ecosystems
The shift toward digital banking offers major operational and financial benefits for both consumer households and commercial enterprises.
Unprecedented Speed and Operational Efficiency
Traditional financial processes that once required days or weeks—such as opening an account, depositing paper checks, or securing loan approvals—now occur within minutes. Automated verification systems, biometric authentication, and digital document signing streamline administrative workflows. For businesses, instant payments and digital invoicing significantly improve cash flow management and operational predictability.
Enhanced Personalization Through Advanced Analytics
Digital banks process vast quantities of transactional data to gain deep insights into consumer behavior. Machine learning algorithms analyze spending patterns in real time to offer customized financial advice, flag subscription costs, set automated savings targets, and present tailored loan or credit card offers. This transition from reactive account hosting to proactive financial guidance provides users with actionable tools to improve their financial health.
Democratization of Financial Services and Inclusion
Digital banking infrastructure has significantly lowered the cost of serving customers, extending formal financial services to previously unbanked and underbanked populations worldwide. Individuals in remote or underserved areas can open accounts, receive wages digitally, access small credit lines, and build a credit history using non-traditional data sources, all without ever stepping foot inside a traditional bank branch.
Key Challenges and Emerging Risks
While digital banking introduces immense convenience and operational agility, it simultaneously creates new security, technological, and regulatory challenges that demand constant vigilance.
-
Sophisticated Cybersecurity Threats: As financial transactions move online, cybercriminals deploy increasingly sophisticated strategies, including automated phishing campaigns, credential stuffing, account takeover attacks, and ransomware. Protecting digital assets requires heavy continuous investment in multi-factor authentication, end-to-end encryption, and continuous network monitoring.
-
Algorithmic Bias and Systemic Risks: automated underwriting algorithms rely heavily on historical data and predictive modeling. If these models contain unexamined biases, they can inadvertently discriminate against specific demographics during loan evaluations. Furthermore, highly interconnected digital financial networks can amplify system-wide outages or liquidity runs if panic spreads rapidly across social media platforms.
-
Loss of Human Touch and Branch Accessibility: Complete digitalization can create friction for customers facing complex financial issues that benefit from human consultation, such as mortgage restructuring or probate estate management. Additionally, older demographics or communities lacking reliable high-speed internet access risk being left behind as physical branches close.
Future Trends Shaping the Next Decade of Banking
The evolution of digital banking shows no signs of slowing down. Several emerging technological frameworks promise to further reshape the financial industry over the coming years.
Artificial Intelligence and Conversational Banking
Generative AI and advanced natural language processing are replacing rigid automated phone menus with highly sophisticated virtual assistants. These conversational agents resolve complex customer queries instantly, detect fraud in real time, and offer dynamic financial coaching based on predictive market trends and individual spending data.
Embedded Finance
Embedded finance refers to the seamless integration of financial services into non-financial digital platforms. Consumers can now access point-of-sale financing, purchase insurance policies, or complete one-click payments directly within ride-sharing platforms, e-commerce storefronts, and social media channels without navigating to a separate banking application.
Central Bank Digital Currencies and Blockchain Integration
Central banks across the globe are researching and testing Central Bank Digital Currencies (CBDCs). Built on advanced ledger technologies, CBDCs aim to provide a digital alternative to physical cash while improving settlement speeds and reducing cross-border transfer costs. Alongside CBDCs, institutional adoption of blockchain technology continues to streamline interbank clearings and trade finance execution.
Frequently Asked Questions
What is the primary difference between a traditional bank and a neobank?
A traditional bank operates physical brick-and-mortar branches alongside digital services and offers a full suite of traditional banking products. A neobank is a digital-only financial platform that operates entirely online without physical branches, typically focusing on streamlined checking, savings, and mobile payment features with lower fee structures.
Are funds deposited in digital banks as safe as those in traditional banks?
Yes, provided the digital bank or its partner institution is fully licensed and insured by government bodies, such as the Federal Deposit Insurance Corporation in the United States. FDIC insurance protects eligible customer deposits up to two hundred and fifty thousand dollars per depositor in the event of an institutional failure.
How does digital banking protect my financial data from cyberattacks?
Digital banks employ multiple layers of enterprise security, including end-to-end data encryption, biometric login verification, multi-factor authentication, real-time AI fraud monitoring, and strict tokenization protocols that obscure actual account numbers during digital transactions.
What happens if a digital bank’s mobile application or server goes down?
During temporary server outages, debit cards usually continue to function for offline point-of-sale transactions, though app access and online transfers may be paused briefly. Digital banks maintain redundant backup servers and disaster recovery frameworks to restore online access as quickly as possible.
Can I deposit physical cash into a digital-only bank account?
Yes, most digital banks facilitate cash deposits through participating retail partner locations, select networked automated teller machines (ATMs), or direct transfer from an linked external traditional bank account. However, specific deposit limits and retail service fees may apply.
What is open banking and how does it benefit consumers?
Open banking is a secure system that allows consumers to give third-party financial applications permission to access their banking data through secure APIs. This enables consumers to use unified budgeting software, automated investment tools, and instant payment services that consolidate information from multiple accounts into a single platform.
Will digital banking completely eliminate physical bank branches?
While physical branch networks are consolidating rapidly, they are unlikely to disappear entirely. Instead, physical branches are shifting toward specialized advisory centers focusing on complex financial decisions—such as wealth management, commercial lending, and real estate purchases—while routine daily transactions move permanently to digital channels.